Thursday, February 23, 2012

The Key to Understanding Today’s Republicans: Reverse-Evolution


Evolution didn’t come up at the Republican debate last night,  but if it had then I’m sure that Rick Santorum would have been just as scary—and incoherent—as he was when asked about contraception and other “social” issues.

One must listen closely to the following words to grasp how seemingly clueless and desperate the Republican base has become if they think that Santorum is their man. When John King of CNN, the debate moderator in Arizona, asked Santorum to explain why he believes contraception is dangerous, the candidate responded by talking about "the increasing  number of children being born out of wedlock in America, teens who are sexually active. ...  How can a country survive if children are being raised in homes where it's so much harder to succeed economically? It's five times the rate of poverty in single-parent households than it is in two-parent homes."
Set aside whether his statistics are right. The only rational conclusion to take from these words -- if the year is 2012 and not 1512 and we aren’t about to hire Torquemada as president-- is that Santorum was arguing //for// contraception. And yet in almost the next breath Santorum proceeded to talk about cutting funding to Planned Parenthood. In his mind, apparently, he was really making a case about fundamentally changing the culture in America, dictating from Washington how people are to have children and with whom, and certainly in wedlock. He appears to think he’s running for pope – or maybe the vacant office of Inquisitor-- more than president.
And make no mistake: there is a formidable consistency to the views of Rick “Sanctus” Santorum. In an interview in 2008, Santorum criticized the teaching of evolution in public schools and boasted about getting creationist language into the No Child Left Behind Act. “I think there are a lot of problems with the theory of evolution,” he said, adding that it promotes “atheist” views.  

The tale of how this man became the New Republican Standard-Bearer—how a has-been senator, disliked for his zealotry by fellow Republicans and Democrats alike even when in office, has come to be the Great Red Hope—tells a larger story of today’s GOP. Even allowing for long-term trends such as the demographic shift of the country toward the South and West—and thus growing social conservatism—it hasn’t always been easy to understand the evolution of the Republican Party. How did a truly Grand Old Party of brilliant champions such as Lincoln, Taft and Eisenhower (and yes, even Nixon) become a party of genial dolts like George W. Bush and Rick Santorum?

But perhaps Santorum's religious beliefs offer a clue. Today’s Republicans are so convinced the theory of evolution must be wrong that they are actually standing up for reverse-evolution. And they are not just talking the talk; they are walking the walk.  

That is, the Republican Party is devolving toward greater and greater stupidity. As “conservative” ideology gets more absurdly detached from reality and actual life in all its complexity, Republicans must find ever-dumber champions to ensure that their presidential candidate doesn’t dissolve into laughter when he delivers his GOP-base-approved talking points (or, in the case of Mitt Romney, descend into incoherence in trying to defend once-reasonable-middle positions like Romneycare). Just as George W. Bush was a pitiful heir to step into the shoes of an Eisenhower, or a Nixon, or even a Reagan, Santorum may actually be dumb enough to make W. look brilliant.

Next up in 2016: the cast of Gorillas in the Mist. Yes, Rick, you are related. 


Monday, February 20, 2012

The 'Earth First!' Candidate vs. the 'Birth First' Candidate


(A Satire, with apologies to Jonathan Swift)

Thank Heaven. Really. I hope we all understand by now that it can only be the Almighty, acting through his modern-day Messenger on earth, Rick “Sanctus” Santorum, who has rescued us from what was becoming a far-too-complex and esoteric campaign debate about Big Government versus Small Government and shifted the focus back to where it belongs. Back to people. To a choice between the people candidate and the anti-people candidate. Santorum versus Obama. Let no one claim any longer that they can't  understand the stakes of this presidential campaign.

And for this moment of clarity we  must also thank Rick Santorum himself. Deploying the brilliant intellect that led Senate staffers in 2006 to vote him “no rocket scientist” (he came in second after Jim Bunning, whose brilliance was entirely limited to his pitching arm)-- a mind that Santorum has used impressively, day after day, to wrench the annoying complexities of the real world into an unchanging and consistent ideology (check out, most recently, his masterful condemnation of all government bailouts) – he has criticized Obama for a “phony theology” that “elevates the earth above man.” We had long suspected this to be true of our profoundly inhumane and un-American president, of course. Even back in Chicago, when Obama was a community organizer, it was said that he favored inner-city buildings over their occupants. As president Obama has opted for banks over borrowers, the health care system over the insured, and of course government before individuals. Anti-people through and through.

Rick Santorum, by contrast, is all about supporting people. Grownup people. Unborn people. It doesn't matter. We want them all here with us, as many of them as we can muster, to assume their rightful dominion over the earth and its animals. After all, it says so right in Genesis (or chapter one of the Santorum campaign platform). He has opposed amniocentesis and prenatal testing as mere precursors to abortion. One of Santorum's supporters, Tony Perkins of the Family Research Council, expanded on Santorum's remarks today by denouncing China's one-child policy as immoral, saying that Beijing needs to let more people be born so they can come up with "creative ideas." 

Make no mistake: This is an election between the "Earth First!" candidate and the "Birth First!" candidate.

There's just one sticky problem with this inspiringly pro-people view, a minor detail that I'm sure we can easily address. There are already a lot more people than our high-tech, increasingly automated and robotized world economy can employ. We have a couple generations of "left-behinds" who can't find work. and now that there are computers that can score better than most of humanity on IQ tests, it's going to get tougher. As the New York Times noted recently, quoting a study by researchers at MIT, "automation is rapidly moving beyond factories to jobs in call centers, marketing and sales — parts of the services sector, which provides most jobs in the economy." That is one reason why even as corporate spending on equipment and software has increased 26 percent since the end of the recession, payrolls have remained flat. Even jobs as simple as truck driving aren't safe any longer, the Times says: Google recently announced it has developed robot-driven cars that have logged thousands of miles on American roads "with only an occasional assist from human back-seat drivers." Even our new drone-heavy military--traditionally a place to offload our many young people without job prospects or education--is going to need fewer of them. 

So if we're going to have a lot more people under a Santorum presidency, we need to figure out what to do with them. As a devout (there is no other word for it) Santorum supporter, I have done considerable research on this question of how to take care of all these people whom we love and treasure. At first, I wondered whether we could adapt Jonathan Swift's ingenious  "Modest Proposal" for ending the problem of overpopulation and food shortages in Ireland in the 18th century.  As Swift wrote, with the same sort of brilliant simplicity that our very own Rick applies to hard issues, why not solve both problems with one solution? "I have been assured by a very knowing American of my acquaintance in London," Swift wrote, "that a young healthy child well nursed is at a year old a most delicious, nourishing, and wholesome food, whether stewed, roasted, baked, or boiled."   

There is a lot to this idea, even today. After all, if people are so loveable, they must be tasty too. But, let's be practical: culinary tastes have moved on since then, and there might be some moral quibbles about such a solution in our very advanced, modern world. (Rick might not like it either.) So I would like to offer my own Modest Proposal. We don't have enough jobs, the islands of the world are all inhabited already, and yet it wouldn't do to have all these unoccupied new people flooding our cities, causing traffic jams and crime waves.

What if, instead, we gathered all these wonderful excess people in one place, so they could all be together, and those of us who are lucky enough to still have jobs wouldn't have to worry about them? I seem to recall  solutions like that in the past, which worked quite well for a time and were described by their designers as very pro-people, or at least humane. I think they were called concentration camps. Hmm. Rick, Tony and I will have to look into that further and get back to you...


Friday, February 17, 2012

What Santorum Doesn't Get


Rick Santorum's fierce condemnation of "bailouts" before the Detroit Economics Club on Thursday was a good ideological fix for those who like to mainline pure market smack. But Santorum's remarks misrepresented or ignored so much of the actual history of the financial catastrophe of 2008 and the auto industry crisis that one must ask: Does he understand that history? Not to mention economics. Not to mention the job of president. All of which makes me wonder in turn: were all those Capitol Hill staffers right when they voted him second-dumbest senator in his final year in 2006?

Santorum criticized the Bush administration's "bailout" of Bear Stearns, but actually what occurred was nothing like that. The New York Fed issued a $30 billion loan to J.P. Morgan to faciliate the sale of Bear Stearns, collateralized by the underwater investment bank's assets. The deal resulted in the dissolution of that investment bank, which no longer exists. Not much of a bailout.

More significantly, Santorum said he believed the financial industry and economy would have recovered on their own without government intervention. True, there have been major, legitimate questions raised about the nature of the TARP bailout -- by me, among many others -- and whether, in the end, it was "injurious to capitalism," as Santorum said. But nearly every mainstream economist agrees that Wall Street was so insolvent by then that a total collapse of the financial system, and very likely another Depression, would have resulted had the government not intervened. As former Fed Vice Chairman Alan Blinder and Mark Zandi, an economist at Moody's who advised John McCain in the 2008 campaign, concluded in a 2010 paper, absent the bailouts of the banks and auto companies, the unprecedented lending policies of Ben Bernanke's Fed and other extraordinary measures, America's GDP would have been 11.5 percent less, with 8 and half million fewer jobs and a federal budget deficit that would actually be higher.

Thus, Santorum was also pushing the boundaries of credibility when he denounced the Obama administration's rescue of the American auto industry, suggesting that the Big Three would have fared well on their own. "Would the auto industry look different than it does today? Yes it would," Santorum said. "Would it still be alive and well? I think it would be alive and just as well, equally if not better."

The problem with that view? He has no evidence. The evidence on the other side of the ledger, meanwhile, is overwhelming. A study by the Center for Automotive Research in 2010 found that more than 1.14 million jobs were saved in 2009 alone because of the bailout.

Santorum also suggested that the steel industry has fared well absent government help, even though it has only a fraction of the jobs it had a few decades. The industry has lost at least another 50,000 jobs in just the last decade.

Santorum may well boast of his ideological consistency. His connection to economic reality is another question entirely.

Thursday, February 16, 2012

Mad-As-Hell-America: A Profile of A Real-Life Howard Beale


Dylan Ratigan, who rants for a living every afternoon on MSNBC, has been occasionally compared to Howard Beale, the iconic TV anchorman in the prescient 1976 movie Network who urges Americans to shout out the window: “We’re as mad as hell and we’re not gonna take this anymore.” But to hear Ratigan explain his anger, he’s more in the mold of Martin Luther, a renegade priest on a holy mission to save capitalism from the corruption of its body and soul.

“I am a true believer still,” Ratigan says, despite a career that has transformed him from a financial groupie for Wall Street into a fiery crusader for reform, or possibly revolution. A man who inveighs with pop-eyed rage against the “Greedy Bastards” –the title of his new best-selling book-- of Wall Street and Washington, and who has proved to be a harbinger for the populist Occupy Wall Street movement.

Overcaffeinated, hyper-verbose, rattling off arcane jargon that even his TV guests sometimes don’t understand, Ratigan remains at heart very much what he started as: a creature of the financial world. No surprise: Ratigan came of age working the arterial heart of financial journalism, beginning at Bloomberg, where he rose from hotshot mergers & acquisitions reporter to global managing editor; then moving to CNBC, which covers Wall Street in somewhat the way Pravda once covered the Soviet Union-- with passionate devotion and without asking fundamental questions about the legitimacy of the system.

It was at CNBC, in 2008 and the beginning of 2009, that Ratigan first began doing his Howard Beale imitation. Once part of the crowd of Wall Street cheerleaders, Ratigan suddenly found himself alone and appalled. He was outraged that neither his journalist colleagues nor anyone in the regulatory world was openly acknowledging the truth: that the worst financial crash since the Depression meant that a great “experiment” in financial capitalism had failed. For more than a decade, the financial system had “distributed risk” around the world on the theory that it could be spread out to those who could best bear it, and everyone could keep track of it with super-complex formulas and really powerful computers. Securities based on subprime mortgages were only part of the experiment.

“The idea was that people who can most afford to take the risk take it, and you end up with a tremendous super cycle of credit that creates an explosion of activity. That was the theory of the experiment.  I was fully on board with that,” he says. The ambitious child of a single mother from upstate New York, Ratigan began his career as a journalist learning finance at the feet of Warren Buffett, attending his famous annual meetings in Omaha. “His point always was that the point of capitalism is to invest capital and align investor interests with entrepreneurs. … Bloomberg’s purpose was to enhance the quality of that decision-making. Financial journalism seemed noble to me in that context because I felt I was participating in the parsing of that information,” he says.

For many years the “experiment” seemed to work. The economy was humming, despite the housing bubble and growing alarms about income inequality; it was the era of expansion and seeming mastery of capitalism that economists called “the Great Moderation.”  “It was awesome. I enjoyed it. I bought a Porsche,” says Ratigan, who still lives in Tribeca half a block from Citigroup headquarters, or what he calls “South Hedge-istan.” “My personal life was totally validating my professional narrative.”

But as it turned out, no one really knew what the risks were and where they were going, and the huge Wall Street institutions that everyone thought were smart enough to regulate themselves no longer cared about how much risk they were carrying or shifting onto others. They also knew the government would save them, violating one of the central rules of capitalism: if you bet wrong, you pay.  In the end this almost destroyed the entire financial system of the United States. When banks began offloading their risks to shareholders and then implicitly to the government as they grew “too big to fail,” capitalism ceased to function. Fundamental fixes were needed.

Yet rather than bravely acknowledging this disaster, Ratigan says, Washington and Wall Street began a giant cover-up, or a papering-over of the problem. Ratigan, from his perch among the movers and shakers interviewed every day on CNBC, recalls his astonishment when then-Treasury Secretary Hank Paulson called the heads of the major banks down to Washington and forced them all to take TARP funds, no questions asked. That was the beginning of the pretense that the system as it was could simply go on, with government help. “It was a total betrayal of everything I believed in… I actually felt personally betrayed,” he says.

The next big inflection point came when he was sitting with one of his high-level Wall Street sources, Larry Fink of BlackRock, one of the world’s largest asset managers, who told him that the private sector now believed the commercial paper market sustaining Wall Street was a fraud. There too the government stepped in, also asking very few questions about the confidence game on which the banks had come to depend.

As he describes it in his book -- titled, with his usual subtlety, “Greedy Bastards: How We Can Stop Corporate Communists, Banksters and other Vampires from Sucking American Dry” --  Ratigan was having lunch one day with a bank CEO who remarked to him: “Dylan, do you see what is going on here? This is the largest theft and cover-up in American history.” Ratigan says things didn’t come fully into focus for him until he saw the crisis through the eyes of an outsider, his old roommate from Union College. “We were standing in my kitchen in Tribeca, and he said:  ‘So, this is criminal.’ I looked at him and said, yeah, it is. He said, ‘So what are you going to do about it. You have a TV show.’”

As CNBC, they were beginning to get a bit uncomfortable with Ratigan’s on-air rants. The head of CNBC, Mark Hoffman, called him one day in 2009. “He’s like, a little confused. He asks, ‘What is your objective?’ My contract was coming up, and my rhetoric was becoming permanent. They would tolerate a few rants in September, October, November, December, but I’m like a dog with a bone. I’m like, you didn’t fix the experiment. They won’t even admit the experiment failed. They just hit reset button. And said, here’s more chips.”

Yet he wasn’t fired, Ratigan insists. (Neither Hoffman nor a CNBC spokesman returned a call asking for comment.) It was more that he had had enough and MSNBC, eager to build out its new liberal theme, came calling. “I decided to leave for the simple reason that by the time it gets to March of 2009 it is stunningly clear to me that there is no body in the government, nobody in the Democratic party, nobody in the Republican party, and nobody in the media who is going to pursue this. Nobody. They’re just going to walk away and listen to Tim Geithner and Larry Summers and Barack Obama and the apologists … [who] speak the platitudes of capitalism but they don’t enforce the policies of capitalism.”

Now, Ratigan says, on MSNBC he gets to offer “a narrative that has not existed in the mainstream media before.” Many people still don’t know what to make of the Wild Man of MSNBC or his book, though it has hit the best-seller list.  Even those sympathetic to reform don’t necessarily endorse what he says. As the Boston Globe wrote in a review, “Ratigan turns selfish bankers, doctors, and oil executives into cartoon enemies — variously identifying them as bastards, pirates, vampires, and zombies — and muddies what appears to be sincere frustration with banal slogans of outrage: ‘The truth will set you free - but first it will piss you off.’” (Ratigan claims the cartoonish nature of the book was intentional, a way of demystifying and taking the tensions out of the debate.)

Other critics say that Ratigan’s favorite hobbyhorses, such as requiring banks to have higher capital requirements, are in fact being implemented under the Dodd-Frank financial reform law and already moderating Wall Street behavior in profound ways. In a recent New York magazine article, Gabriel Sherman wrote that Dodd-Frank had been far more successful than Ratigan and other skeptics said, that Wall Street is being tamed (or “emasculated,” as the dramatic cover line puts it.) Nonsense, says Ratigan.  “Why did they open up Panama” with a free-trade agreement? he says.  “It’s not like we’re creating jobs. There’s no real industry there. But it provides an exemption from the entire Dodd-Frank structure.” (Supporters of the Panama free-trade agreement say the pact protects the U.S. right to impose Dodd-Frank and other “prudential measures” adopted by Congress.)

Some Ratigan skeptics are kinder, even as they … keep their distance. “He’s basically the left wing equivalent of the tea party,” says Liaquat Ahamed, the Pulitzer Prize-winning author of Lords of Finance. Ahamed praises Ratigan and MSNBC for bringing “attention to a whole lot of things, particularly income inequality.”

What does Ratigan think should have been the real solution to the financial crisis? Admit the huge banks aren’t working, nationalize them, immediately bypass them by providing a “2 percent lending facility” to all small businesses in America, Ratigan says. Instead, “you’re giving the banks money that they’re not giving to the marketplace.” Instead, he says, “the Obama administration’s became the world’s Hope-ium dealers,” handing out money, merely anesthetizing against the pain. The Occupy Wall Street movement whose anger he anticipated, he says (but which he keeps arms’ length from), was a response “to the fact that two years of Hope-ium wore off, and people felt the pain again.”

Last August, Ratigan appeared to totally lose it on air, screaming (in a video that went viral) that “tens of trillions of dollars are being extracted from the United States of America.” Since then he’s taken solace from his allies on Occupy Wall Street, and the new green shoots of capitalism are occurring healthily in places like the venture-capital community of Northern California. But Ratigan admits it’s a little strange to be an avowed capitalist in the midst of all those liberals—who wants to save the system so ‘we can have capitalism for the next 500 years in America.”

And so Dylan Ratigan rants on, intent on changing the future, but borne back ceaselessly into his past…

Monday, February 13, 2012

Is Wall Street 'Castrated' -- Or Just Lying Low?


Gabriel Sherman lends a sympathetic ear to the newly meek Masters of the Universe in his cover story in New York magazine, which appears under the ridiculously over-the-top headline "The Emasculation of Wall Street."  "On Wall Street, the misery index is as high as it’s been since brokers were on window ledges back in 1929, " he writes. And more, unprodded by prosecution or even any serious civil cases, the onetime bad boys of the Street are proving themselves endearingly conscience-stricken: along with the complaints about reduced pay "is something that might be called soul-searching" about Wall Street's many sins and its wildly overcompensated contribution to the U.S. economy, he writes.


OK, there is a lot to what Sherman says. Despite the holes in Dodd-Frank, reduced compensation and increased capital requirements are going to snuff out or marginalize some of the riskier businesses that got us into this mess. And perhaps the most hopeful sign in his article is that Wall Street has become so unexciting that the best minds in the nation may think about going into real engineering--or Silicon Valley--rather than financial engineering. As Liaquat Ahamed, the Pulitzer-winning author of the great "Lords of Finance," put it to me in a conversation today: "Banks and bankers are going to become boring." 
For the moment, yes. But what worries me is not what happens this year or next--but ten and 15 years from now. The fact is, the giant banks are going to remain giants, and there is nothing to fix the too-big-to-fail problem beyond a host of as-yet-unwritten "living wills" that are supposed to tell regulators how to liquidate the banks in a crisis. The largest surviving banks—mainly Citi, JPMorgan Chase, Goldman Sachs, Bank of America, Morgan Stanley, and Wells Fargo—are growing bigger and more global relative to the rest of the industry. They have already snapped up weak sisters at fire-sale prices (Bank of America swallowed Merrill Lynch, and JPMorgan gulped down Bear Stearns). They are pushing out smaller banks in key areas, having increased their overall market shares in deposits, mortgages, credit cards, home-equity loans, and small-business loans. 
And they are only getting harder to unwind, no matter what all the new rules say. “In my judgment, as best as I can recount history, not just the last three years but the history of mankind, I can’t think of a single case where we were able execute the orderly wind-down of a systemically important institution—especially one with an international footprint,”  Gerald Corrigan, the widely respected former head of the Federal Reserve Bank of New York, told me for a cover story last May. “There’s a reason why we’ve never been able to do it—and it’s because it’s so damn hard to do it. It’s really that simple." 
Beyond that, at more than $700 trillion (yes, that's trillion), the derivatives trade is already much larger than it was during the 2008 crisis. And meager as it is, Dodd-Frank is in the process of being gutted on Capitol Hill (never mind what might happen if Mitt Romney gets elected president, since he has vowed to repeal it).  Regulators are starved for staff.  With a staff of only 712 (roughly unchanged from the 1990s, when financial products where much less complex), the Commodities Futures Trading Commission must regulate markets seven times the size of the futures market it used to oversee.  “Until we complete this task, the American people remain at risk,” Chairman Gary Gensler warned me and my colleague Stacy Kaper in an interview with National Journal last December. "We are midstream” in rule-writing and in requiring firms to report their trading positions, he admitted. “The only thing that we would have right now is the data that banks and others are voluntarily reporting.” Even after the rules are written, Gensler said, “we won’t necessarily have the cops on the beat to oversee the market.”
As James Kwak writes today in The Baseline Scenario, Sherman's article tends to depend on the sob stories of master Street manipulators like Jamie Dimon and well-known outside critics. "The story’s featured voices are ones that are not on Wall Street and have been critical of it for a long time, such as Paul Volcker and John Bogle," Kwak writes. "There are certainly bankers saying that the business is getting tougher, but that’s a cyclical thing. Profits were lower in 2011 than in 2010 because the economy was weaker in 2011 than in 2010. ... My main worry is that the regulations we have are still fundamentally reactive."
Kwak is right. Washington will never catch up. And depend on it, Wall Street will figure out a way around those regulations, as long as the structure of these giant firms remains intact. Wall Street always does.

Wednesday, February 8, 2012

Martha Coakley's Comeback: From Error-Prone Candidate to Housing Advocate


In January 2010, Martha Coakley's gaffe-filled loss to Scott Brown in the Massachusetts special election to replace Ted Kennedy marked one of the most humiliating moments for Democrats in the Obama era. Her defeat presaged the GOP takeover of the House later that year and the stranglehold that tea party politics has had on national policymaking in the last two years.


But Coakley's looking pretty damn good since then, making me wonder: has she been more effective from Massachusetts than she would have been from Washington? Even as all the attention has been focused on  Elizabeth Warren, the consumer-finance firebrand who is in a tight Senate race with Brown, Coakley has quietly built up an impressive record as attorney general in Massachusetts. Coakley has been, until recently, one of the few holdouts to resist the deal announced today with major banks over documentation fraud and other past abuses. More than 40 states have agreed to the $26 billion settlement but Coakley has been paying heed, until now, to advocates who say the deal is a cave-in, and she has insisted on her  right to sue.  Indeed, Coakley has launched what is considered one of the most promising lawsuits in the nation over unfair and deceptive business practices.  The Boston Globe recently called her "a national leader on behalf of homeowners caught up in the long-running housing crisis."


Under the legal theory being used by Coakley, the big Wall Street banks can and should be held accountable for the criminal nonbanks they were in bed with -- the liability-laden firms that the banks often bought up as the mortgage bubble expanded.  According to Kathleen Engel of Suffolk University Law School, the documentation scandal that has cropped up in the last year or so--raising doubts about whether investment trusts ever obtained proper ownership of many of the loans and whether they can foreclose on mortgages--can be used to pin liability on these "vertically integrated" Wall Street giants and cost them some serious money in fines.


“The environment is ripe for consumers, state attorneys general, and federal agencies to pursue claims against entities further up the securitization food chain, especially given increasing evidence that Wall Street failed to observe the formalities that might have insulated arrangers and investors from most consumer claims,” Engel and a co-author, Thomas Fitzpatrick, an economist at the Federal Reserve Bank of Cleveland, write in a forthcoming article in the Harvard Business Law Review. “The designers of securitization sought to insulate investors and arrangers by erecting legal structures that would shield them from liability arising from the actions of loan originators.” But “those structures are not as solid as investors and arrangers expected.”

Then, on Wednesday, Coakley made an appearance at the Center for American Progress in Washington arguing for the success and constitutionality of Massachusetts' health care law--which, as it looks better and better as a program, is going to prove more and more embarrassing for Mitt Romney. The  leading GOP candidate has discarded it under withering GOP criticism of Obamacare, which was modeled on it. But it appears to be working: according to a statewide survey taken in 2010, 94.2 percent of Massachusetts' nonelderly (19–64) residents reported being covered, a significant increase over the 86.6 percent estimate of 2006. The survey also showed first-time reductions in emergency department visits and hospital inpatient stays as well as improvements in self-reported health status Even right-wing wraith Ann Coulter argued last week that the law works, though she made the argument that if applied federally it would be unconstitutional, backing up the Court of Appeals for the Eleventh Circuit, which declared that the individual mandate in the Affordable Care Act (ACA) unconstitutional. Coakley argued against that on Wednesday.    


 Last week, Coakley also did what the Obama administration should have done long ago and pressured the acting director of the Federal Housing Finance Agency, Ed DeMarco--who oversees Fannie Mae and Freddie Mac--to reduce loan principal payments for underwater mortgagge holders and do more to prevent "unnecessary foreclosures."


For all her failings as a Senate candidate, Coakley is looking pretty effective as a state attorney general. I wonder if we will see her on the national scene again at some point...

Tuesday, February 7, 2012

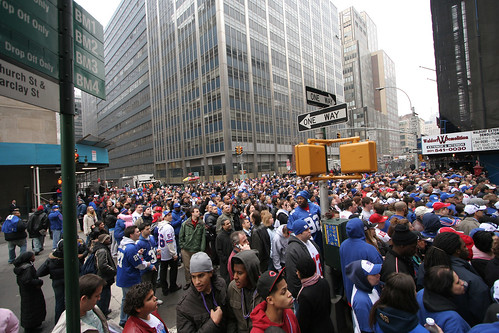
The Giants Get a Parade, Iraq Vets Get ... Dinner


With Obama now rising in some polls, Romney seems to be running out of good talking points these days. So here's a freebie for ya, Mitt. Look, we certainly don't want to begrudge the New York/Jersey Giants their just deserts. But isn't there something just a little lopsided about the fact that the Super Bowl winners are getting a ticker-tape parade through Manhattan today, while the Obama administration prefers to restrict the honors for our war veterans to a polite dinner?

OK, fine, the Giants actually //won// something, and America's devastating and horrifically costly experience in Iraq was so far from a win that we may end up with little more than Saddam-lite, as my colleague Yochi Dreazen has written.

But let's have a sense of proportion, shall we? According to Veterans for Common Sense, America has now suffered 108,974 total war zone casualties since 9/11/01, most of them in Iraq. That includes 6,211 dead. Yet when was the last time you heard about a national event honoring our recently withdrawn troops from Iraq?

If they don't get a parade, can we at least give them a Wall?

Monday, February 6, 2012

Can Barack Emulate Clint?


Clint Eastwood's implicit plug for Barack Obama in last night's halftime-at-the-Super Bowl ad for Chrysler, in which the ironic actor declared optimistically that it's only "halftime in America," made me wonder whether the presidential race between Romney and Obama is going to play out like the ending to another famous Eastwood performance. In 1964's "A Fistful of Dollars," Clint's character outlasts what seems sure to be his demise by revealing that he has a steel chest plate hidden beneath his poncho. Clint, known only as The Stranger, taunts his opponent to "aim for the heart" but the bullets bounce off, and he wins the gunfight.

Now Obama, whom many on the Right are still scurrilously casting as a Stranger to this country, must hope that the fistful of dollars that Congress reluctantly granted him to resurrect the economy--and the auto industry--will produce enough of an economic protective shield to withstand the relentless barrage being aimed at him by Romney. As I have written previously and as Paul Krugman noted today in his column, certain pathological conditions such as long-term unemployment mean that things are not OK despite one of the few truly positive jobs reports to come along in a long time. In a recovery that is still full of more Bad and Ugly than Good (sorry, I'm an Eastwood aficionado), Obama may still need to make history for an incumbent to overcome current jobless levels and get re-elected.

But Clint's pitch for Chrysler was a telling reminder that the president does indeed have some good-news stories to tell about the economy. And one of the biggest stories starts in Mitt "Let the Markets Work" Romney's home state of Michigan. It's not just Chrysler that has made a comeback; General Motors is likely to report its highest ever income for 2011, the Wall Street Journal reports today. Romney, recall, vigorously opposed the auto bailout.

The real question is whether the Obama team can forge a consistent and inspirational message reflecting a coherent economic philosophy, one that will effectively counter Romney's simplistic--but clear--appeal to free markets. It's time for the president to stand up and bravely declare that what passes for economic wisdom in Washington today is a debunked mythology, and that America has succeeded, long term, largely thanks to a mixed economy of free markets and government support.

If Obama can do that successfully, he might just find that he gains, if not Teflon, then at least an aura of the old Clint Eastwood movie toughness come November.


Saturday, February 4, 2012

It's No Ordinary Recovery. So Why Should It Be An Ordinary Election?


In the last day we've heard experts in the political world issuing various sounds of celebration (Obama) and consternation (Romney) over the new jobless numbers and the booming stock market. But the reaction on both sides is probably premature at best. Just as this is no ordinary economic recovery, it's wrong to assess the presidential election odds using the ordinary metrics.

True, the Obama-ites have reason to peek up from their defensive crouch, and the Romney camp has been forced to duck into one. The drop in the unemployment rate to 8.3 percent continues what will be the president's best hope of re-election: an upward trend in hiring that persists until election day and undermines Romney's claim that only he can turn the economy around. We've now had five consecutive monthly declines in the unemployment rate, and if that continues, voters may react more to the forward motion than the absolute numbers, even though the current 8 percent levels are still hard for an incumbent to overcome and the jobless rate is likely to remain higher than it was at Obama's inauguration (7.8 percent) by election day. The Dow's return to levels not seen since May 2008, before the final financial collapse, is also a major milestone back into positive territory for Obama.

But keep in mind: this is still the worst economic crisis since the Great Depression. "We have never seen unemployment this high for this long," says Heidi Shierholz, an economist at the Economic Policy Institute, who notes that jobless rates have now exceeded 8 percent for a record 35 months, surpassing the early '80s recession mark of 27 months.  As I've previously written, an issue that could be more telling for Obama's future could well be the long-term unemployment rate--workers who have been out of a job for more than six months, in many cases a year or more, and can't find a new one no matter how hard they try. "What's really different in this recession is that we have people who really want to be working and really can't find work," Betsey Stevenson, until recently the Labor Department's chief economist, told me recently.

The labor market simply isn't clearing as readily this time around, in part because of long-term unemployment, in part because of business uncertainty over Europe, regulation, political gridlock and other issues, in part because of other pathological conditions that the nation has rarely, if ever, dealt with before. That's especially true of the underwater housing market that Obama only now seems to be realizing is far worse than he thought. "I'll be honest, the programs we've put forward didn't work at the scale we'd hoped," Obama said this week, and on Saturday he pressed the point home in his weekly radio address, urging Congress to pass a plan he took far too long to develop: using the Federal Housing Administration to guarantee refinanced loans at lower rates for underwater borrowers.

But Obama is still not using the sort of strong-arm tactics he could be employing, critics say, such as forcing Fannie and Freddie to take more action to help mortgage holders (they are in receivership, after all). That would require extraordinary political courage. And in the Bizarro world of Washington, it's somehow OK to ignore the "moral hazard" of spending hundreds of billions of dollars to bail out banks with no questions asked, while the idea of helping the victims of those banks is still deemed a sin that might undermine the beautiful purity of capitalism.

As a result, the mortgage and foreclosure crisis remains a spreading infection that has gone largely untreated. It has prevented a resurgence of demand in a consumer economy that, because of stagnant wages, had become dependent on debt and refinancing for growth until the crash. Both the size of the housing bubble and the implosion that ensued also were unnaturally severe because of the sheer amount of housing and securities fraud that fed the mania. Many banks may still be technically insolvent because of the devalued mortgage-based securities and loans they have on their books. Even so, "from the beginning, all the proposals for relief were too small," whether from the administration or the Congress, says Diane Thompson of the National Consumer Law Center.  "They underestimated the amount of fraud. And I think they overestimated the good will of the bankers."


What the Obama team, and the Congress, failed to estimate well at all was the unusual nature of this economic disaster. Much will depend on the political success that Obama has pinning a good part of the blame on George W. Bush and the Republican-led Congress, versus the skill with which Romney pins much of it on Obama. And that is why when it comes to this presidential election, the usual numbers don't mean a lot. 

Wednesday, February 1, 2012

The Rich Fantasy Life of Newt Gingrich


Is it just me, or is there something very offputting, and not a little weird, about the way Newt Gingrich keeps talking in ever greater detail about what he will do his first day in the White House? Even in conceding a devastating loss in Florida--one in which many voters spurned him on the basis of moral character and electability, according to exit polls--Gingrich went on and on last night about moving into the WH. He said he'll be so busy his first day--signing,  "two hours after the inaugural address," executive orders abolishing "all of the White House czars," opening the embassy in Jerusalem and "recognizing Israel" (sic), and reinstating Reagan's anti-abortion "Mexico City policy" -- that he and Callista will barely have time to have fun at the inaugural balls.

That's what you might call a rich fantasy life. And not only, by his lights, is Newt all but certain to be president, he will be a world-historical one. "This is //the// most important election of your lifetime," he told his supporters, deploying the usual self-referential superlatives. He embellished his speech with his usual grandiose references to Abraham Lincoln (the Gettysburg Address), Thomas Jefferson ("I pledge to you my life, my fortune, and my sacred honor") and the other Founding Fathers. He even used the royal "we."

If it were just an isolated incident, one might write off Newt's rambling concession speech to exhaustion and shock, and, as he said, the lack of a teleprompter ("I'm going to have to wing this," Newt said). But it's not isolated. As Jacob Weisberg noted in a fine Slate piece ("Is Newt Nuts?"), Gingrich exhibits "certain symptoms--bouts of grandiosity, megalomania, irritability, racing thoughts, spending sprees--that go beyond the ordinary politician's normal narcissism."

All of which suggests that, while Gingrich is unlikely to get the nomination at this point, his enduring fantasy of himself as a great figure in history may propel him to carry on this primary race far longer than reality might dictate. He said last night he's going all the way to the convention. He talked about coming back again and again. I think he believes it.